What Is Interest and Why Do Banks Pay It? Explained Simply
SUMMARY OF THIS ARTICLE
- Interest is the money a bank pays you for letting it use your savings. Think of it as rent: the bank rents your money, and interest is the rent it pays.
- Your money does not sit still in a vault. The bank lends most of it to other people and businesses, and those borrowers pay the bank a higher rate of interest.
- The gap between what the bank earns from borrowers and what it pays you is how the bank makes its money.
- A simple example: if you keep $100 in savings at a 5% yearly rate, the bank pays you $5 in a year. That rate is only an example — real rates go up and down.
- Interest matters for ordinary savers because it rewards patience: your savings grow a little while you wait, and that small growth adds up over time.
The Jar on the Kitchen Shelf
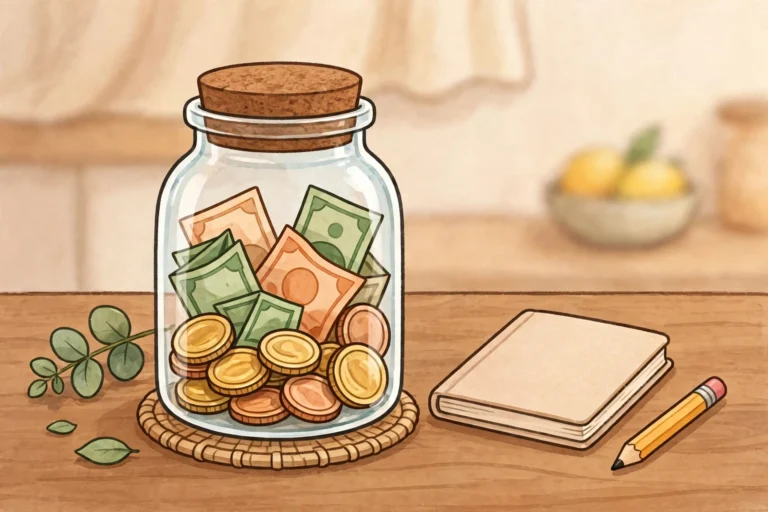
Every family seems to have a jar like this. It sits on a kitchen shelf, and coins go into it one by one. A few coins after shopping. The change from a bus fare. A note folded up small on a good week. The jar fills slowly, and there is something deeply satisfying about hearing the coins clink.
What happens if you take that jar to the bank instead of leaving it on the shelf? The coins are the same, but something new starts to happen: the money begins to grow, a little at a time, all by itself. The bank pays you for keeping your money with it. That payment is called interest.
Most people have heard the word, but few know what it really means, or why a bank would pay you for holding your money. This article answers that in plain words.
What Is Interest, in Simple Words?
Interest is the price of using someone else’s money. When you borrow money, you do not just pay it back. You pay it back plus a little extra. That little extra is the interest — the cost of having the money now instead of later.
Think of it like borrowing a neighbour’s ladder for an afternoon to clean your gutters. Now imagine you needed it for a whole month. Your neighbour might ask for something in return — a few dollars, a bag of apples, a favour later. Money works the same way: the borrower uses the money now, the lender waits, and interest makes the waiting fair.
Think of interest as rent. You know how rent works for a house: you live in someone else’s house, and you pay them every month for the use of it. Money is rented in just the same way. When a bank holds your savings, it is renting your money, and interest is the rent it pays you.
One thing to keep clear: interest is always talked about as a rate, a percentage. You will see numbers like 2%, 4%, or 5%. A rate tells you how much extra money changes hands over a year, compared with the amount involved. A 5% yearly rate on $100 means $5 of interest in one year, as we will see in a moment.
Interest Is Rent for Your Money
Imagine you own a spare bicycle that you ride only on Sundays. Your neighbour’s bicycle breaks, and she needs one for two weeks while hers is being fixed. She offers to pay you $10 to borrow yours. You agree. She brings it back in good shape and hands you the $10 — the rent for your bicycle.
Your savings work the same way. You have money you do not need right now. It could sit in a drawer, doing nothing. Or you could let the bank use it for a while, and the bank will pay you rent for it. That rent is the interest on your savings.
Here is what makes money different from a bicycle. A bicycle can only be lent to one person at a time. Money can be split, shared, and passed along. The bank takes your deposit, joins it with the deposits of thousands of other savers, and puts that large pool of money to work.
There is a second lesson hiding in the rent idea. Rent is always a share of the value. A big house costs more rent than a small room. A new car costs more to hire than an old one. Interest works the same way: the more money you save, the more interest you earn, because the bank is renting more money from you. It is simple maths — more money lent means more rent paid.
What Happens to Your Money Inside the Bank?
Many of us picture a bank as a giant safe, with our money sitting in a vault in a neat pile, waiting until we come back for it. That picture feels safe, but it is not how banks really work.
Your money does not sit still. The moment you deposit it, the bank puts most of it to work. It lends it to people who need it now: a young couple buying a home, a baker opening a shop, a student paying for a course. Those borrowers pay the bank interest on their loans, and that interest is higher than the interest the bank pays you. The difference between the two is where the bank’s profit comes from. Our guide to how banks make money tells the full story.
Does that mean your money is gone? No. The bank keeps enough cash on hand to cover everyday withdrawals, and it follows strict rules about how much it must hold back. A savings account promises exactly this: your money is there when you need it, and it earns interest while it waits.
Picture the bank as a bridge. On one side stand the savers, people with a little extra money they do not need today. On the other side stand the borrowers, people who need money today. The bank is the bridge between them. It carries money from savers to borrowers and charges the borrowers for the crossing. The savers get a share of that charge — your interest.
Without the bridge, savers would earn nothing and borrowers would wait years to save up. Money has travelled a long way to reach the bank, as our story about who invented paper money shows — the bank is simply the latest stop on that journey.
A Simple Example: $100 at 5%
Let us work through one example together.
Imagine you put $100 into a savings account at a rate of 5% a year. Please note: that 5% is only an example we have chosen to make the maths easy. Real rates are different, and they change over time.
Five per cent means five out of every hundred. So on $100, the bank pays you $5 in one year. You started with $100, and after one year you have $105. The $100 is still yours. The $5 is the rent the bank paid you for using it.
Now try a bigger amount. If you saved $1,000 at that same example rate, the bank would pay you $50 in one year — five out of every hundred, ten hundreds in a thousand. You would have $1,050 at the end of the year. And a smaller amount, for the coin jar on the shelf: $50 at 5% a year earns $2.50 in one year. Not a fortune, but two and a half dollars you did not have before, earned while you did nothing except leave the money in the bank.
What if you keep the money in the bank for a shorter time? Interest is usually worked out over a full year, but the bank still pays you fairly for part of a year. Keep $100 in savings for six months at our example rate, and you would earn about $2.50 — half a year, half the interest.
Why do banks talk about rates instead of fixed amounts? Because a rate works for everyone, no matter how much they save. A rate of 5% means the same deal for the person saving $50 and the person saving $50,000 — each one earns five out of every hundred they saved. The rate is the price tag.
One warning is worth giving here. When you see a savings rate advertised anywhere, check the small print. Some accounts pay a higher rate only for a few months, then drop to a lower one. Some pay more only if you leave the money untouched. Some charge a monthly fee that eats up the interest. The headline number is never the whole story — read the terms and compare two or three accounts before you choose.
The Mirror: When You Borrow, You Pay the Rent
When you borrow money, you become the renter, and the bank becomes the owner. You take the bank’s money and use it now — to buy a car, fix a roof, or start a small business. In return, you pay the bank back, plus interest: your rent for using the bank’s money. It is the same idea as savings interest, only the direction is reversed.
Imagine you borrow $100 from a bank at 10% a year — an example rate, not a real one. At the end of one year, you owe the $100 you borrowed, plus $10 of interest. You pay back $110 in total. The $100 was the loan. The $10 was the rent.
When people talk about what a loan is, they are really talking about renting money. A mortgage is renting a large amount of money for a long time, to buy a house. In every case, the borrower pays rent, and the rent is called interest.
The mirror also explains why borrowing can be a trap if you are not careful. The rent keeps coming as long as you hold the money. Borrow $100 at our example rate of 10% a year, take two years to pay it back, and you owe roughly $10 of interest for each year. Borrow only what you truly need, and pay it back as quickly as you can.
Borrowing also lets people do things they could never do by saving alone. A young family could wait twenty years to save enough to buy a house outright, or borrow now and move in while their children grow up in a real home. Interest is the price of that head start. Used wisely, it buys time. Used carelessly, it buys trouble. The difference is not the interest itself. It is the plan behind the borrowing.
Why Is Loan Interest Higher Than Savings Interest?
The bank pays savers, say, 5% in our example. It charges borrowers, say, 10%. Why the gap? Why not pay savers the same rate it charges borrowers?
The gap is the bank’s living. Think of a fruit seller at the market. She buys apples from a farmer for $1 each and sells them to shoppers for $1.50 each. The 50 cents in between is not greed. It pays for her stall, her transport, her time, and the apples that go bad before they sell.
A bank works the same way. It “buys” money from savers at one price — the savings rate — and “sells” it to borrowers at a higher price — the loan rate. The gap pays for everything the bank needs: staff, branches, computers, security, and the losses when some borrowers cannot pay back. What is left over is the bank’s profit. Just remember the fruit seller.
There is another reason for the gap: risk. Not every borrower pays back. A business can fail, a person can lose a job, a harvest can fail. When a borrower cannot repay, the bank loses money, so the gap builds in a cushion for those losses. If the bank charged borrowers exactly what it paid savers, one bad loan could sink it.
This is also why the interest you earn on savings is almost always lower than the interest you pay on a loan. It is not a trick. It is the shape of the business: the bank sits in the middle, takes a cut for doing the work and carrying the risk, and passes the rest on to you. When you compare banks, look at both sides, the way you would compare two fruit sellers before buying your apples.
Why Do Interest Rates Go Up and Down?
If you have checked your savings rate one year and found it different the next, you are not imagining things. Rates move, sometimes a little, sometimes a lot. Here is why, in simple words.
The biggest force behind your savings rate is the country’s central bank — a big, official bank that sits above all the other banks and sets the pace for the whole system. When the central bank raises its main rate, borrowing becomes more expensive, and banks can charge more on loans. Savings rates often rise too. When it lowers its rate, loans get cheaper, and savings rates usually fall as well.
Why does the central bank move its rate at all? Mostly to keep prices steady. When prices rise too fast, it often raises its rate to cool things down: higher rates make borrowing more expensive, so people borrow less and spend less, and prices rise more slowly. When the economy is slow, it may lower its rate to make borrowing cheaper, so businesses invest and families spend.
Competition between banks is the second force. Banks want your deposits, because deposits are the raw material of their business. If one bank offers savers a better rate, others may raise theirs to keep their customers. Two banks on the same street can offer very different rates, and the difference is pure gain for the saver who notices.
A third force is the type of account. Money locked away for a year usually earns more than money you can take out tomorrow, because the bank can plan with it. Money you can empty at any moment is less useful to the bank, so it pays less for it. That is the trade-off: easy access earns less, patience earns more. Rates are the result of all these forces pushing and pulling at once. You cannot control the central bank or the economy. What you can control is your choice of account, and how long you leave your savings alone.
Why Does Interest Matter for Ordinary Savers?
With all this talk of banks, it is easy to lose sight of the person this matters most to: the ordinary saver. You.
First, interest is a reward for patience. Life tempts us to spend everything now — a new phone, a sale at the shops, a takeaway on a tired evening. Spending is easy, and saving feels like missing out. Interest tips the balance the other way. It says: wait, and your money will grow. Not by a lot, and not overnight, but it will grow.
Second, interest helps your savings keep up with rising prices. A loaf of bread costs more this year than it did five years ago. If your money sits in a drawer, it buys less bread every year, because prices climb while your money stays still. Interest pushes back against that. It does not always win, but it slows the loss, and in good years it can even beat it. Money in the bank stands a chance.
Third, interest turns saving into a habit with a visible result. There is a quiet joy in checking your balance and seeing a little more than you put in. You deposited $100, and now the balance says $105. The extra $5 is simply there, because you left the money alone and let the bank pay its rent. That small surprise is a powerful teacher, especially for children.
Fourth, interest makes an emergency fund stronger. Most of us need a small cushion for a broken fridge, a car repair, or a sudden bill. An emergency fund in a savings account is there when you need it, and while it waits, it earns interest — so the next emergency is a little easier to handle.
Finally, interest matters because it is honest money. Nobody gave it to you as a favour. Nobody tricked you into it. You lent your money, the bank used it, and the bank paid you rent. That is a fair deal, and fair deals are worth understanding.
Small Habits That Make Interest Work for You
Knowing what interest is matters, but using it well is a skill of its own. A few small habits go a long way.
Start by keeping your savings separate from your spending money. If your savings sit in the same account as your everyday money, they will quietly disappear into coffees, snacks, and small treats. Open a separate savings account, even if it holds only a little at first. Our guide to what a savings account is shows how to set one up.
Next, compare before you choose. Banks do not all pay the same rate. Look at the rate, but also at the fees, the minimum balance, and how easily you can take your money out. A high rate with a heavy monthly fee can leave you worse off than a lower rate with no fee at all.
Then, save a little on a regular rhythm. The amount matters less than the habit. Ten dollars a week, set aside the day your pay arrives, beats a hundred dollars saved once in a blue moon. Regular saving builds the balance, and a bigger balance earns more interest, because the bank is renting more money from you.
Try to leave your savings alone when you can. Every time you dip into savings for something that is not a real need, you shrink the balance, and a smaller balance earns less rent. That does not mean never touching your savings — that is what they are for, in a real emergency. It means pausing before you touch them for a want. Sleep on it — many wants fade overnight.
Lastly, teach a child. Show them the coin jar, then show them a savings account, and let them watch a small balance grow. Money can work while you sleep, and patience pays.
Frequently Asked Questions
What is interest, in simple words?
Interest is the money paid for using someone else’s money. When you keep savings in a bank, the bank uses your money and pays you interest — like rent — for the use of it. When you borrow from a bank, you pay interest to the bank for using its money.
Why does a bank pay me interest on my savings?
Because your deposit is the raw material of its business. The bank lends your money to borrowers, who pay the bank a higher rate of interest. The bank keeps part of that as profit and passes part of it on to you as savings interest.
How much interest will I earn on $100?
It depends on the rate your bank offers, and rates change over time. As a simple example, if your savings rate were 5% a year, you would earn $5 on $100 in one year. Always check the rate on your own account.
Is savings interest the same as loan interest?
They are the same idea, running in opposite directions. Savings interest is what the bank pays you for using your money. Loan interest is what you pay the bank for using its money. Loan rates are almost always higher — that gap is how the bank makes its profit.
Why do interest rates go up and down?
The biggest reason is the country’s central bank, which raises or lowers its main rate to keep prices steady. Banks follow that lead, and they also compete with each other for deposits. The type of account matters too: money locked away for longer usually earns a higher rate.
Can I lose money in a savings account?
In normal times, your savings in a bank are safe, and the bank must return your deposit when you ask for it. In many countries, savings are also protected by a government-backed scheme up to a set limit. The real risk is different: if prices rise faster than the interest you earn, your money slowly buys less — so compare rates and keep your savings in an account that pays a fair return.
More from Zorium Daily
- Why Do We Use Money Instead of Trading Things?
- What Is a Savings Account and How Does It Work?
- What Is a Loan and How Does It Work?
- How Do Banks Make Money?
The next time you check your bank balance and see a small amount of interest added, you will know what it really is. It is not a gift, and it is not a mystery. It is rent — the bank paying you for the use of your money, while it lends that money on to people who need it now. Your patience makes the lending possible, and the borrowers’ payments make your interest possible. The coin jar on the shelf was a good start. The bank simply gives that jar a job to do.